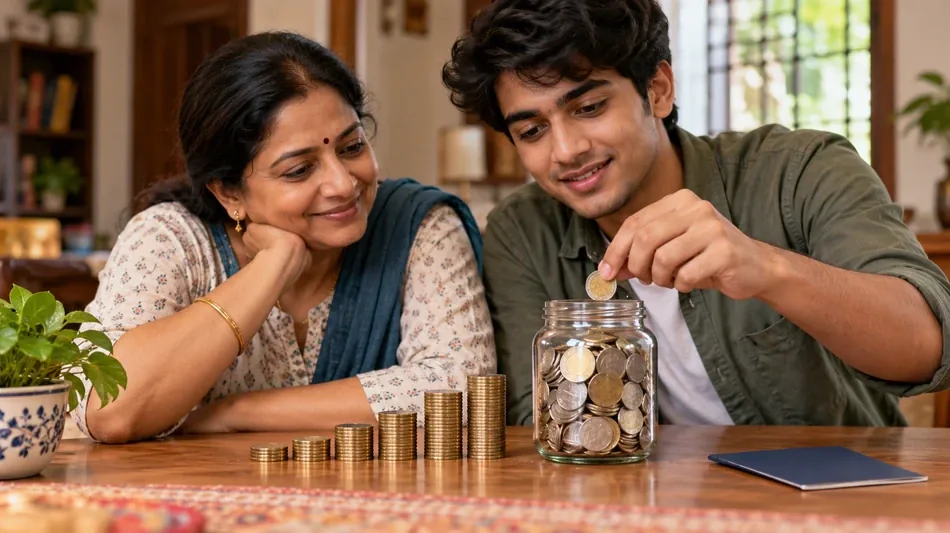
NPS Vatsalya offers three choices when a child turns 18

 London
 9 °C

 Manchester
 9 °C
 Glasgow
 8 °C
 Dublin
9 °C
 Belfast
8 °C
 Washington
 12 °C
 Denver
11 °C
 Atlanta
14 °C
 Dallas
22 °C
 Houston Texas
22 °C
 New Orleans
20 °C
 El Paso
23 °C
 Phoenix
24 °C
 Los Angeles
22 °C
San Diego
23 °C
San Francisco
18 °C
Chicago
18 °C
Minneapolis
11 °C
Seattle
11 °C
Portland
11 °C
Salt Lake City
11 °C
Las Vegas
21 °C
Miami
24 °C
Jacksonville
 20 °C
San Antonio
 24 °C
Bermuda
21 °C
Nassau
13 °C
Iqaluit
 -2 °C
Yellowknife
2 °C
Anchorage
 6 °C
Fairbanks
1 °C
Barrow
1 °C
Calgary
0 °C
Edmonton
15 °C
Winnipeg
1 °C
Goose Bay
9 °C
Halifax
8 °C
Boston
10 °C
Ottawa
12 °C
Toronto
14 °C
Detroit
13 °C
Cleveland
12 °C
New York
14 °C
Baltimore
11 °C
Philadelphia
13 °C
Nuuk (Godthåb)
-5 °C
Hong Kong
 27 °C
Singapore
28 °C
Melbourne
24 °C
Canberra
 18 °C
Adelaide
15 °C
Darwin
32 °C
Perth
 18 °C
Fort Worth
22 °C
Honolulu
27 °C
Sydney
20 °C
Johannesburg
18 °C
Dubai
28 °C
Mumbai
29 °C
Zürich
8 °C
Tokyo
19 °C
Seoul
18 °C
Delhi
17 °C
Beijing
12 °C
Riyadh
24 °C
Prague
7 °C
Pennsylvania
9 °C
Valletta
20 °C
Manama
30 °C
Warsaw
8 °C
Stockholm
11 °C
NPS Vatsalya subscribers gain control of their accounts at 18 and may continue, transfer the corpus to regular NPS or exit under specified withdrawal rules.
NPS Vatsalya subscribers gain control of their accounts at 18 and may continue, transfer the corpus to regular NPS or exit under specified withdrawal rules.
But what happens when the child turns 18? Who gets the accumulated money, and what options are available for managing or withdrawing it? Here’s what you need to know.
What is NPS Vatsalya?
NPS Vatsalya is a contributory savings scheme for minors under the National Pension System (NPS). It is regulated by the Pension Fund Regulatory and Development Authority (PFRDA).
The account is opened in the minor's name, with the child as the sole beneficiary. A parent or legal guardian operates it until the child turns 18, and a Permanent Retirement Account Number (PRAN) is issued in the child's name.
Who can invest and what are the contribution rules?
Indian citizens below 18 years, including eligible Non-Resident Indians (NRIs) and Overseas Citizens of India (OCIs), can have an NPS Vatsalya account. The scheme is available irrespective of gender. The parent or legal guardian opens and manages the account on behalf of the minor.
The minimum initial contribution is ₹250, followed by a minimum annual contribution of ₹250. There is no maximum contribution limit. Investments are managed by a pension fund registered with PFRDA. Returns are market-linked and are not guaranteed.
Can you continue NPS Vatsalya after the child turns 18?
The parent or legal guardian manages the account on behalf of the minor until they turn 18. Upon attaining majority, the subscriber (or child) takes charge of the account and is responsible for its management.
The accumulated contributions, investment returns, and benefits belong solely to the subscriber. The account holder has three options after attaining 18 years of age:
Continue: The account holder can continue the NPS Vatsalya account until they turn 21.
Shift to NPS: Transfer the entire accumulated corpus to NPS Tier I under the All Citizen Model or another applicable model.
Exit: Withdraw the accumulated corpus, subject to the applicable exit rules. If the accumulated corpus is below ₹8 lakh, the entire amount can be withdrawn as a lump sum. If it is ₹8 lakh or more, up to 80% can be withdrawn as a lump sum, while at least 20% must be used to purchase an annuity.
How does NPS Vatsalya work after a child turns 18?
When the subscriber/ child turns 18, they must complete fresh KYC and update nominee details to take control of the account.
They can continue investing under NPS Vatsalya until age 21, transfer the entire accumulated corpus to an eligible NPS account, or exit subject to applicable rules.
If no option is exercised by age 21, the account automatically moves to a higher-equity scheme under the same pension fund's Multiple Schemes Framework (MSF).
Disclaimer: This is for informational purposes only. Please visit the official website for the latest updates and applicable rules.
Z.Quintana--HdM